1031 exchange planning
1031 exchange deadlines: the 45-day and 180-day rules
Plan the identification and completion periods for a deferred 1031 exchange, including the earlier tax-return deadline.
Read guide →
Home / Learning center / Local Guides
Local Guides
Winthco Wealth Management · Updated November 19, 2026
A Gardena DST advisor can help compare passive replacement real estate with the responsibilities you want to leave behind. Start by coordinating the property's sale requirements with your broker, CPA, attorney and qualified intermediary. Then evaluate DST costs, control and liquidity independently of the desire to complete an exchange or retire from direct management.
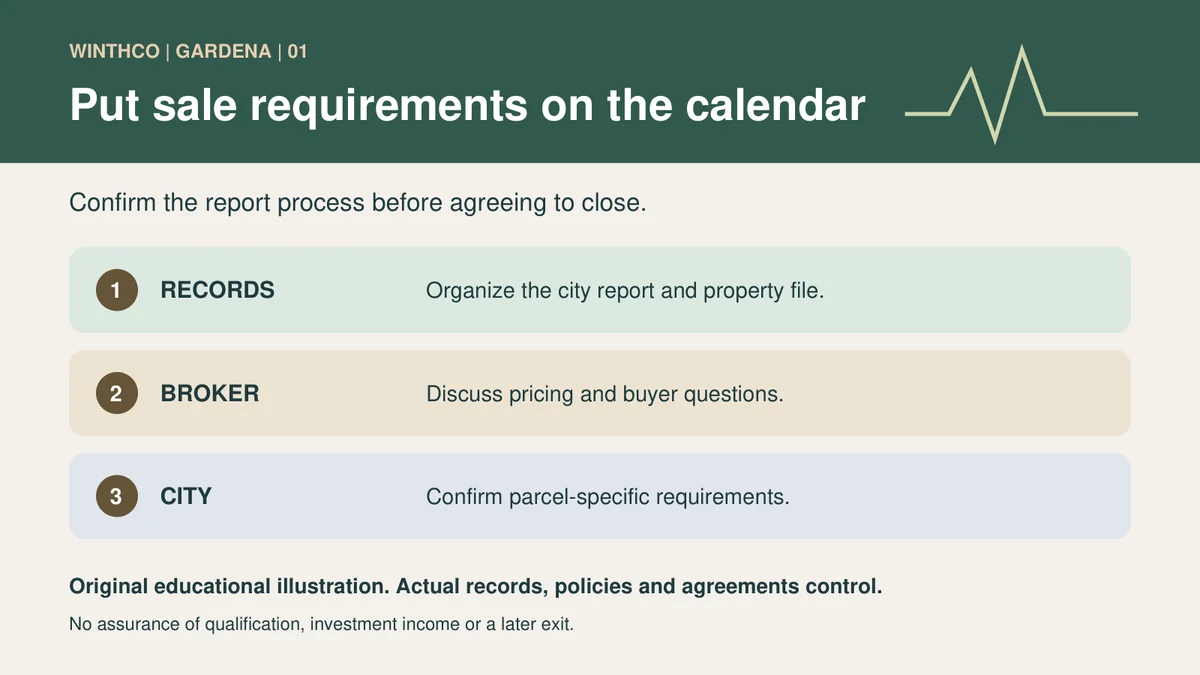
Before choosing replacement real estate, establish what must happen for the existing property to close. Gardena's published Property Information Report application describes a city-record review and inspection process associated with a sale or exchange. Ask your licensed realtor or commercial broker to confirm the current requirements with Building & Safety and counsel. Do not wait until the buyer's final review to discover a document or inspection issue.
Interview the broker about comparable transactions, property-type experience, marketing, tenant communication and compensation. Ask who will coordinate required reports, what information supports the proposed price and how repair questions will be handled. A broker's responsibility for the sale is different from a securities professional's analysis of a DST. Winthco's DST evaluation starting point can help you organize the replacement-investment questions while the sale team handles the building.
Share your timeline and investment range. A Winthco team member will follow up with you.
Gardena's July 2025 report form states that the seller or licensed broker must obtain the report and deliver it to the buyer no later than 15 days before consummation of the sale or exchange. It also calls for the buyer's signed report to be returned to Building & Safety. Confirm applicability, current procedures and any exception or waiver directly with the city and your attorney. This guide does not determine a particular transaction's compliance.
The city's Planning and Zoning page directs owners to Title 18, the General Plan and property maps. Use those resources when a buyer asks about the permitted use of a structure or a proposed change. The report form also explains that the inspection is not an assurance that undisclosed violations do not exist. Treat local review, private inspections and investment analysis as different sources of information rather than interchangeable approvals.
Hypothetical: a Gardena landlord receives an offer with a short closing period, but the sale team has not confirmed the property-report timing. The owner first works with the broker, city and attorney to reconcile the contract calendar. Meanwhile, the CPA and QI prepare the contemplated exchange and an investment professional reviews replacement choices. This is an invented planning example, not an actual client transaction or a promise that a closing can be extended.
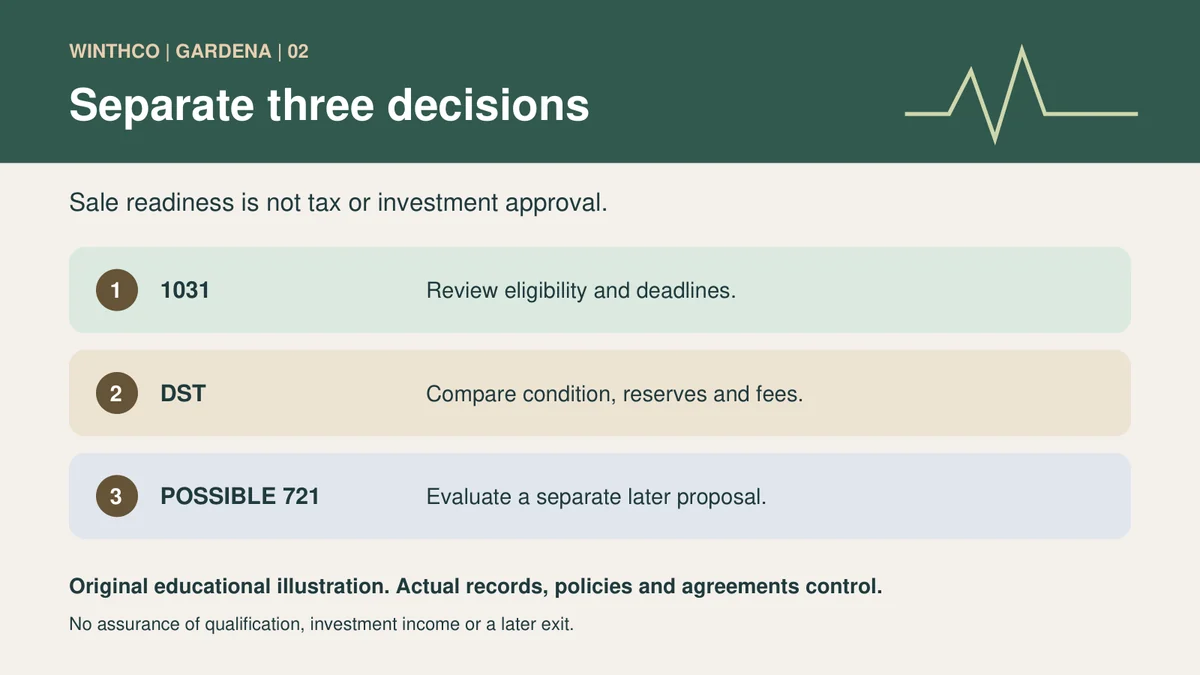
Before closing or receiving sale proceeds. A qualified intermediary structures and documents the deferred exchange; the CPA reviews tax treatment and reporting; the attorney addresses legal ownership, agreements and obligations. Searching for a Gardena DST CPA does not make an investment advisor a CPA. Verify each professional's credentials and responsibilities, and decide who will communicate changes in the closing date.
Section 1031 can defer eligible gain on qualifying investment or business real property, but it does not eliminate tax. The ordinary identification period is 45 days after transfer. Replacement receipt must occur by the earlier of 180 days or the federal return due date, including extensions. Cash or other non-like-kind consideration may cause recognized gain. Ask the QI for the actual dates and written-identification requirements rather than relying on an approximate calendar.
A local reporting requirement does not create an automatic extension of federal exchange deadlines. If a transaction changes, notify the team promptly and have the facts reviewed. Our 1031 deadline explanation can support the discussion. Decide what you will do if an appropriate replacement cannot be secured, including the potential tax consequences, before pressure to finish becomes the main investment-selection criterion.
Discuss your DST questions with Winthco →
A Delaware statutory trust may provide real-estate exposure with less direct responsibility for leasing, repairs and day-to-day property operations. Winthco's overview of DST replacement ownership explains the structure. IRS Revenue Ruling 2004-86 analyzes a specific trust arrangement that can qualify under Section 1031. It is not a blanket approval of every trust or an assurance that a particular purchase meets your tax requirements.
Reduced management work comes with reduced control. A DST investor generally cannot decide independently when the underlying property is sold or personally direct repairs and leasing strategy. Read the governing documents to understand who makes those decisions, what investor approvals exist and what happens when the original plan cannot be followed. Compare those terms with the authority you currently have as a direct owner.
Consider the responsibilities you are actually trying to reduce. Is the problem emergency maintenance, tenant turnover, geographic concentration or the amount of personal time required? A DST may address some management burdens without addressing every financial concern. Moving from a familiar local rental into an unfamiliar property type can introduce a different set of risks. Less involvement is not the same as less exposure to loss.
Read the private placement memorandum, property information and financing terms rather than relying only on a summary. Ask how rental income, operating expenses, reserves and debt service translate into money available for distributions. Separate current collections from assumptions about future leasing. Request an explanation of any gap between the property's operating performance and the distribution shown in marketing materials.
Review property condition and funding for major repairs. A landlord leaving behind a building with recurring maintenance should not assume that institutional management removes capital needs. Ask which repairs are anticipated, how reserves were estimated and who bears costs if spending exceeds the plan. Our DST reserve review describes why the size and permitted uses of reserves matter together.
Identify acquisition charges, selling compensation, ongoing management fees, financing expenses and disposition costs. Ask which recipients are related to the sponsor and whether a later transaction would introduce additional charges. Compare the full contribution with the amount exposed to property economics after costs. Two investments displaying the same distribution percentage may have different expenses, leverage and exit assumptions.
WATCH & LEARN
Tina Colson-Jones of Equity Advantage 1031 Exchange explains the QI's role. Third-party education, not a Winthco affiliation or an individual tax determination. Original resource · Watch on YouTube ↗
Educational context only. The discussion does not establish the suitability, returns or tax treatment of an investment.
Evaluate the sponsor's ability to execute the business plan, the property's tenant mix, lease expirations and competitive position. Ask what happens if a major tenant leaves or expenses increase faster than collected rent. Multiple interests may still share a sponsor, tenant industry, region or lender. A larger number of holdings does not automatically remove concentration risk.
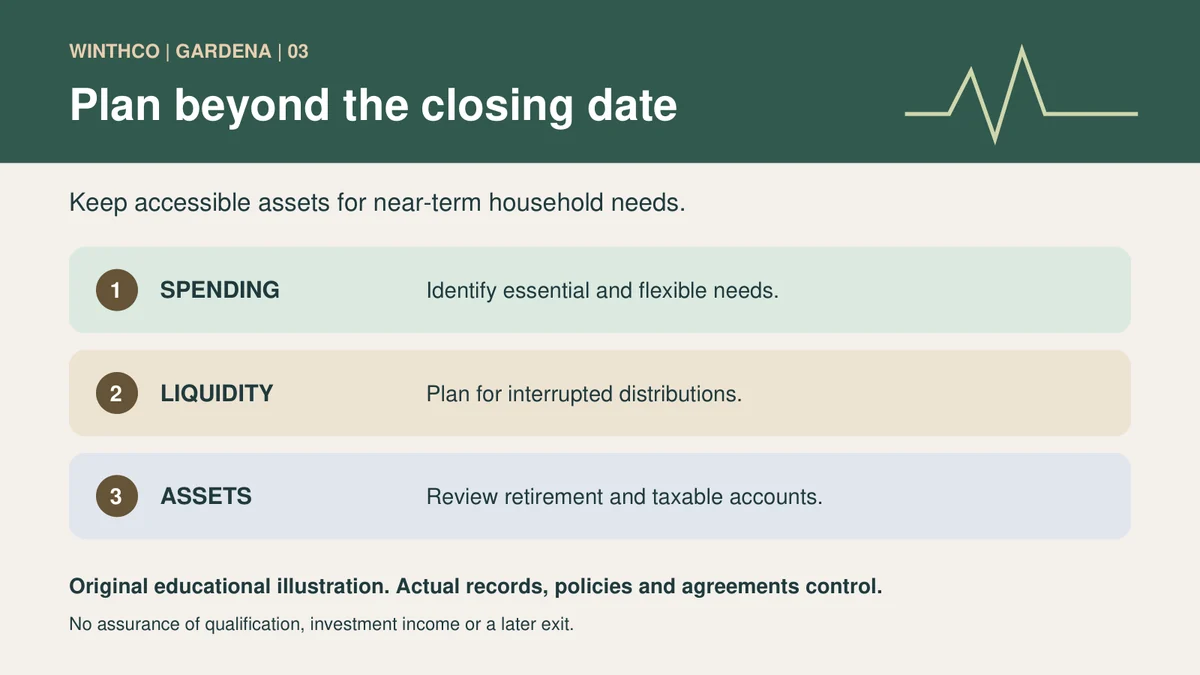
Read loan maturity, interest-rate exposure, lender restrictions and repayment provisions separately from the rental forecast. A planned sale may occur later or at a lower value than expected. Distributions can decline or stop, and principal can be lost. Test the household effect of interrupted cash flow rather than assuming the property will produce a particular payment throughout retirement.
DST private placements generally are limited to accredited investors and offered through a private placement memorandum. The SEC's private-placement bulletin highlights illiquidity and limited disclosure. FINRA's private-placement guidance addresses reasonable investigation obligations for recommending broker-dealers. Ask what supports the recommendation, which uncertainties remain and how the professional is compensated. Eligibility to purchase does not establish that an investment is suitable for your circumstances.
A later Section 721 contribution to a partnership is a separate potential transaction, not an automatic continuation of a 1031 exchange. Ordinary REIT shares and partnership units are not direct Section 1031 replacement real estate. If a proposed DST discusses an eventual UPREIT transaction, have tax and legal advisers distinguish that possibility from the initial investment and explain the terms that would need separate review.
Ask a 721 UPREIT advisor who determines value, who can approve or decline the transaction, what compensation is payable and how liquidity could change. Do not assume a later redemption program will be available when you need cash or that withdrawals will be tax-free. An anticipated future transaction cannot substitute for understanding the DST as it stands today.
Consider the alternative in which the contemplated contribution never happens. Would the original property exposure, fees, management arrangement and uncertain holding period still fit? Review conflicts where related parties might participate on both sides of a transaction. A projected exit path is a scenario to analyze, not a reason to skip the initial offering's risks.
California reporting can continue when property is exchanged outside the state. The Franchise Tax Board requires Form FTB 3840 when California property is exchanged for out-of-state property and California-source realized gain or loss remains unrecognized. Filing generally continues in later years until that deferred amount is recognized. Ask your CPA about the underlying property locations, basis allocation and records needed for any proposed DST.
Review existing taxable investments, 401(k)s, IRAs, retirement-income needs and emergency liquidity with a financial advisor. Qualified retirement accounts are not exchange proceeds. Compare costs, services and access rules before any rollover or transfer rather than assuming every account should move. Coordinate beneficiaries, estate documents and tax planning with the appropriate professionals.
Use either prospect form on this page or the dedicated contact page to share general sale timing and planning goals. Avoid account numbers, tax returns or tenant details in an initial inquiry. Winthco's wealth-management services can be discussed alongside the property decision without presuming an advisory engagement is appropriate. The Gardena map provides city-area context only; it does not identify a Winthco office or determine a parcel's jurisdiction.
City-area context only, not a property boundary or Winthco office.
| Decision | Evidence to request | What to avoid assuming |
|---|---|---|
| Gardena sale readiness | Current city requirements and broker coordination | A report guarantees no property issues |
| 1031 process | QI dates and individual tax review | Local timing extends federal deadlines |
| DST decision | Offering, fee and financing documents | Passive ownership removes risk |
| Retirement plan | Accessible funds and spending needs | A future exit funds current expenses |
Yes. The city's application describes its property information report process. Confirm the current requirements and applicability with Building & Safety and counsel.
No. The city's property review is separate from tax eligibility and securities due diligence. Your advisers must assess those questions independently.
It may reduce day-to-day management responsibilities. Investors also generally give up substantial direct control and still face property and financial risks.
No. It is a separate possible transaction with its own terms and approvals. Evaluate the initial investment without relying on that outcome.
No. It shows the city area for context only. It is not an office marker or a parcel determination.
Sources checked November 19, 2026. This article explains general concepts; your facts and the applicable documents control.
Winthco DST services · Winthco evaluation overview · Editorial standards
1031 exchange planning
Plan the identification and completion periods for a deferred 1031 exchange, including the earlier tax-return deadline.
Read guide →1031 exchange planning
Learn how multiple DSTs affect identification, closings, allocation and concentration risk in a 1031 exchange.
Read guide →DST due diligence
Before exchanging a rental into a DST, review repair budgets, restricted reserves and funding limits. Know which questions to ask before committing.
Read guide →Explore Winthco’s main DST article collection
Share your timeline and investment range. A Winthco team member will follow up with you.