1031 exchange planning
1031 exchange deadlines: the 45-day and 180-day rules
Plan the identification and completion periods for a deferred 1031 exchange, including the earlier tax-return deadline.
Read guide →
Home / Learning center / Local Guides
Local Guides
Winthco Wealth Management · Updated November 21, 2026
A Torrance DST advisor can help compare passive replacement ownership with keeping direct control of real estate. Before that comparison, confirm the property's actual jurisdiction and sale records, involve your tax and exchange team before closing, and decide how much accessible capital the household needs after the sale.
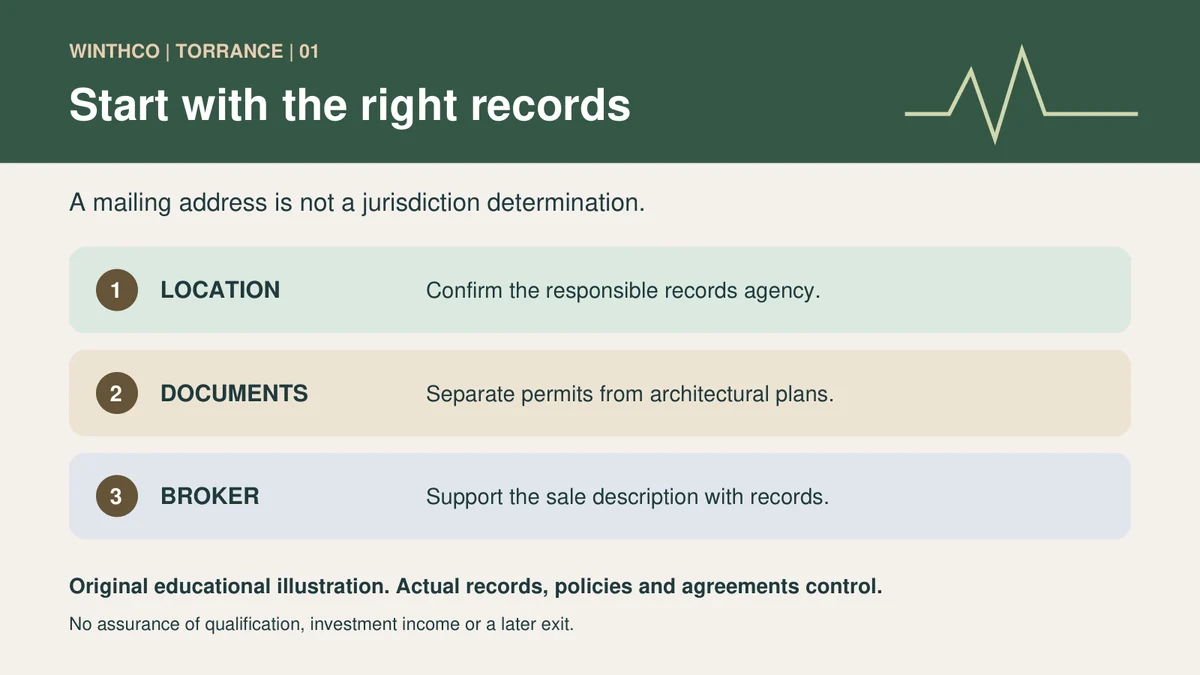
A Torrance mailing address is not enough to identify the agency responsible for property records. The City of Torrance explains that some addresses using its name are outside city boundaries, including areas served by the Torrance Post Office. Confirm jurisdiction before requesting records or describing the property to a buyer. That small distinction can prevent the sale team from looking for documents in the wrong system.
Select an appropriately licensed realtor or commercial broker with experience in the property type you own. Discuss comparable sales, marketing, occupied-property access, compensation and closing responsibilities. Ask how unresolved record questions would be presented to buyers. Winthco's guide to DST replacement ownership can support a separate investment discussion, but an attractive replacement brochure should not determine the asking price or replace sale preparation.
Share your timeline and investment range. A Winthco team member will follow up with you.
The city's property-records page separates active permits, scanned permit records and parcel information. The parcel tool includes zoning, overlay areas and assessor parcel numbers. Building and architectural plans are not available through that search system; the city directs users to the City Clerk or a public-records request. Use the appropriate resource for the question instead of assuming every document is in one database.
Collect leases, rent collections, operating expenses, loan information and records of property work for your own professional team. Ask counsel which disclosures apply and how tenant information should be protected. A map or database entry is a research starting point, not a legal conclusion about permitted use. Resolve inconsistencies with qualified professionals before relying on a description in a listing or valuation.
Hypothetical: an owner preparing to sell a small rental building with a Torrance address learns that the responsible records agency must be confirmed. The broker and attorney reconcile the parcel information while the CPA and qualified intermediary assess a possible exchange. This invented example illustrates coordination, not a client outcome. The property investigation and replacement-investment review remain separate tasks.
Bring the CPA, attorney and qualified intermediary into the discussion before closing or receiving sale proceeds. The broker handles the sale assignment, the CPA evaluates tax consequences, counsel addresses legal matters and the QI structures the deferred exchange. A search for a Torrance DST CPA should lead to verification of an actual CPA's credentials; an investment-advisor title does not establish accounting or legal qualifications.
Section 1031 may defer eligible gain on qualifying business or investment real property when its requirements are met. It does not eliminate tax. Ordinary deferred exchanges require identification within 45 days and receipt by the earlier of 180 days or the federal return due date, including extensions. Cash or other non-like-kind consideration can produce recognized gain. Have the advisers determine the consequences for the actual transaction.
Read our 1031 timing explanation before developing the closing schedule. Then ask the QI what documentation and authorization are needed for the proposed replacement. City record research does not automatically extend federal deadlines. Consider the consequences of not completing an exchange as well as the consequences of buying an unsuitable property merely to meet the calendar.
Discuss your DST questions with Winthco →
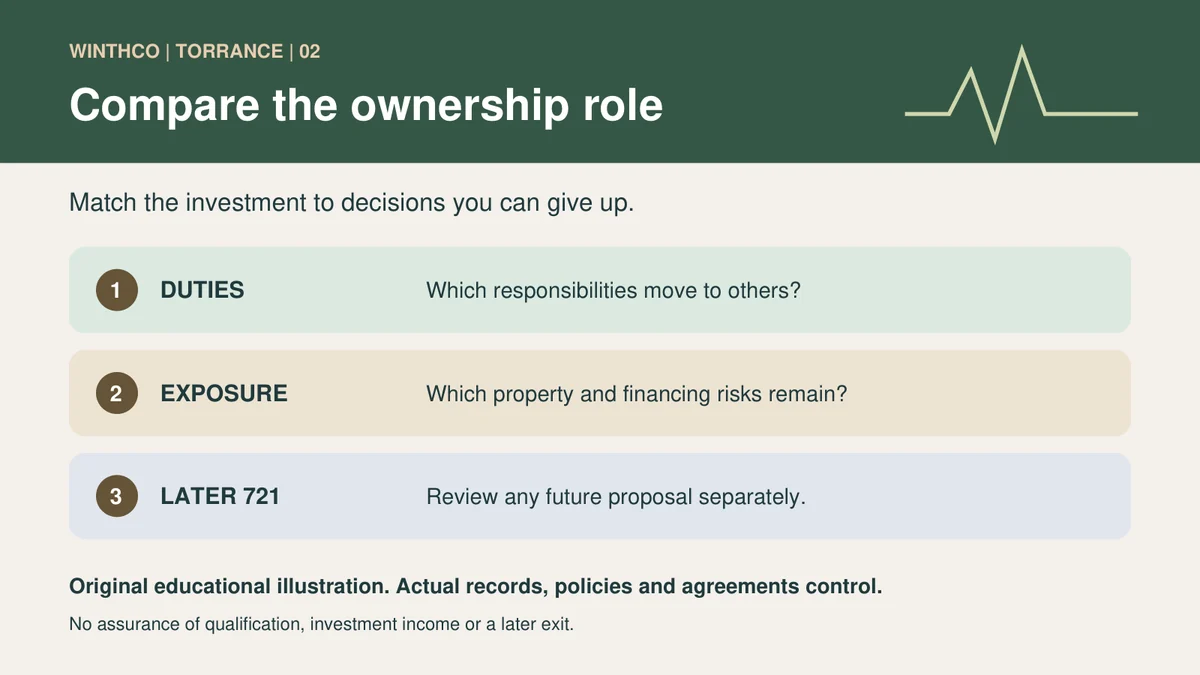
A Delaware statutory trust can reduce direct involvement in leasing, repairs and property administration. In exchange, investors generally give up the ability to make those decisions independently. IRS Revenue Ruling 2004-86 addresses a particular DST arrangement that can qualify for Section 1031 treatment. It is not blanket approval of every trust or assurance that an individual's exchange qualifies. The proposed documents and circumstances still require review.
Use Winthco's DST evaluation questions to compare the responsibilities you would stop performing with the risks you would continue bearing. A landlord may know a building's tenants and repairs from years of direct involvement. A DST investor needs a different information process: offering documents, property reports, financing terms and sponsor communications. Familiarity with your former property does not establish familiarity with the replacement.
Write down the decisions you currently control, including contractor selection, leasing negotiations and sale timing. Ask who would make each decision in the trust and what rights investors retain if circumstances change. If independent control is important to you, reduced management may not be an adequate tradeoff. Passive ownership describes the investor's role, not the absence of business risk.
Compare the drivers of cash flow rather than selecting the largest illustrated distribution. Review tenant credit, lease expirations, occupancy assumptions and property operating costs. Ask which expenses are based on current records and which depend on projections. An investment in another region may reduce some geographic concentration while introducing a market you understand less well. The location of the adviser does not determine the property's exposure.
Read acquisition charges, selling compensation, ongoing fees, financing expenses and eventual disposition charges together. Ask who receives each payment and whether related parties provide services. Expenses can affect both the amount invested in property and the cash available for distribution. Our DST fee review offers background, but only the actual documents establish the charges for a proposed investment.
Examine reserves and expected capital spending alongside the loan. Ask what happens if repairs cost more than anticipated or a tenant leaves before its space can be re-leased. A hypothetical budget with lower rent and higher expenses can help expose dependencies without forecasting an outcome. Do not treat a stated distribution objective as a contractual income promise or compare it directly with gross rent from your old building.
WATCH & LEARN
Tina Colson-Jones of Equity Advantage 1031 Exchange explains the QI's role. Third-party education, not a Winthco affiliation or an individual tax determination. Original resource · Watch on YouTube ↗
Educational context only. The discussion does not establish the suitability, returns or tax treatment of an investment.
DST private placements generally are available only to accredited investors and are offered through a private placement memorandum. The SEC highlights limited disclosure, illiquidity and possible total loss in private placements. Accreditation is an eligibility consideration, not a finding that an investment fits your spending needs. Distributions can decline or stop, and principal can be lost even when the sale and exchange paperwork were completed correctly.
Review sponsor experience and financial capacity without relying solely on marketing claims. FINRA Regulatory Notice 23-08 discusses reasonable investigation when broker-dealers recommend private placements. Ask the recommending professional what supports the recommendation, which documents were examined and which uncertainties remain. A third-party report is useful only if its scope, assumptions and limitations are understood.
Debt can introduce maturity, refinancing and cash-restriction risks. Several DST interests may still share the same sponsor, tenant industry or economic region. Compare those exposures with your other real estate and securities. Diversification is not established simply by counting investments, and it cannot eliminate loss. Avoid using the expected sale date as a dependable source for a time-sensitive household expense.
A possible Section 721 UPREIT contribution is a separate potential transaction, not an automatic step following every DST purchase. Ask a 721 UPREIT advisor to explain who decides whether a proposal occurs, how value is determined and what approvals or conditions apply. Evaluate the original DST on its own merits even when marketing materials discuss a possible future transaction.
Ordinary REIT shares and partnership units are not direct Section 1031 replacement real estate. Have tax and legal advisers explain the proposed structure and how it differs from buying a qualifying DST interest. The same conversation should address fees, related-party conflicts, diversification and any new restrictions. A familiar tax-code section does not make the financial terms interchangeable.
Do not assume that a future contribution will provide immediate liquidity, a particular redemption value or tax-free withdrawals. Ask what choices remain if the proposal is delayed, changed or never offered. The household plan should be workable without depending on an uncertain sequence of transactions. A potential option is most useful when its limitations are understood before capital is committed.
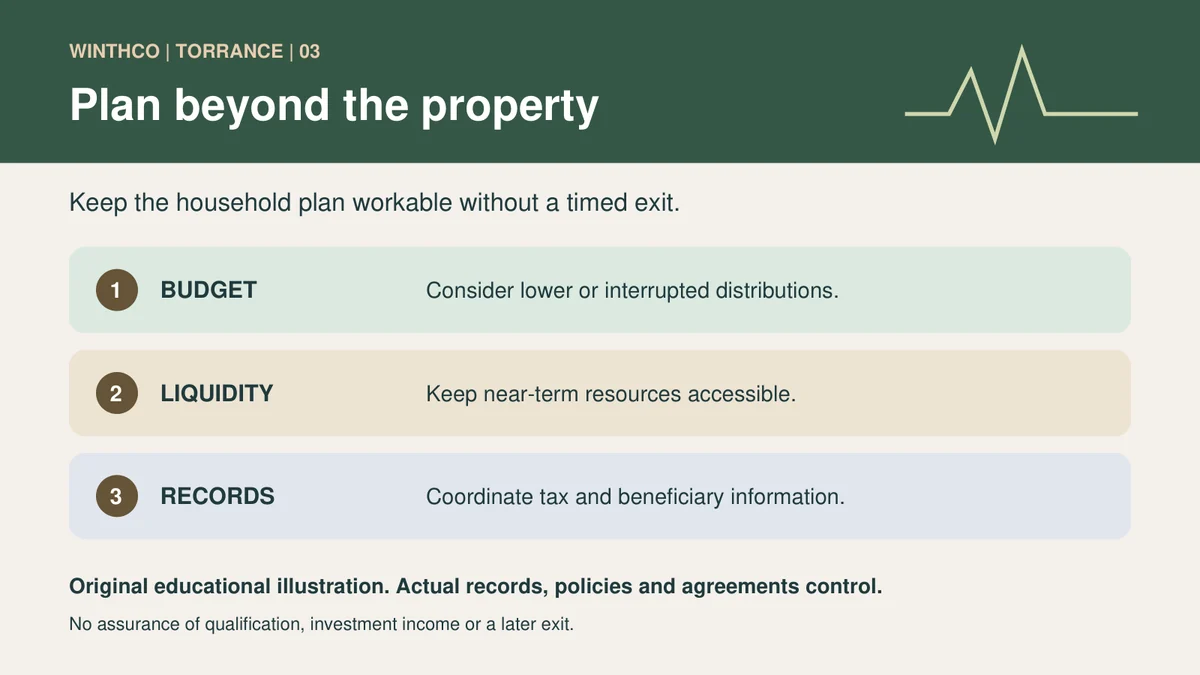
Separate near-term cash needs from capital that can remain illiquid. Review the effect of lower distributions, a longer holding period or an unexpected expense on the household budget. Include existing taxable investments, 401(k)s, IRAs and other resources in a financial-advisor discussion. Retirement accounts are not exchange proceeds, and any rollover or transfer deserves its own comparison of fees, services, protections and access rules.
California sellers considering out-of-state replacement property should ask their CPA about Form FTB 3840 when California-source gain or loss remains unrecognized. Reporting generally continues until the deferred amount is recognized. Maintain basis and transaction records and coordinate beneficiary or estate questions with counsel. A move away from California does not by itself resolve the reporting attached to a prior exchange.
Use either prospect form here or the dedicated contact page to describe general sale timing and planning goals. Do not include tenant details, account numbers or tax documents in an initial inquiry. Winthco's wealth-management discussion can connect the property decision with retirement priorities without assuming every asset should be transferred. The Torrance map provides city-area context only; it does not identify a Winthco office or establish a parcel's jurisdiction.
City-area context only, not a property boundary or Winthco office.
| Decision | Evidence to request | What to avoid assuming |
|---|---|---|
| Sale file | Jurisdiction and supporting records | Mailing address establishes jurisdiction |
| DST choice | Control, costs and property exposure | Passive means no risk |
| Later 721 | Separate terms and approvals | An automatic liquidity event |
| Retirement | Accessible assets and spending needs | Distributions will always continue |
No. The city notes that some Torrance mailing addresses are outside city boundaries. Confirm jurisdiction before requesting records.
The city's records page says those plans are not available through that system. Contact the City Clerk or follow the city's records-request process.
It can reduce direct management duties. Investors generally also have less control and retain financial risk.
Not necessarily. Verify accounting credentials separately and use qualified tax and legal professionals for those questions.
No. It is a separate possible transaction with its own terms and conditions. Do not budget around an assumed redemption date.
Sources checked November 21, 2026. This article explains general concepts; your facts and the applicable documents control.
Winthco DST services · Winthco evaluation overview · Editorial standards
1031 exchange planning
Plan the identification and completion periods for a deferred 1031 exchange, including the earlier tax-return deadline.
Read guide →Risks and due diligence
Learn how to review DST acquisition costs, ongoing expenses, financing charges and exit fees without relying on a single headline number.
Read guide →1031 exchange planning
Learn how multiple DSTs affect identification, closings, allocation and concentration risk in a 1031 exchange.
Read guide →Explore Winthco’s main DST article collection
Share your timeline and investment range. A Winthco team member will follow up with you.