1031 replacement property
DST vs 721 UPREIT after a property sale
Compare DST and 721 UPREIT paths, tax rules, ownership, liquidity, control and risks before a property sale or exchange.
Read guide →
Home / Learning center / California advisor guides
California advisor guides
Winthco Wealth Management · Updated October 22, 2026
A Burbank investment-property owner considering a DST should reconcile permits, leases and sale records before listing, while the CPA, attorney and qualified intermediary review exchange timing before closing. Compare the DST's control, fees and liquidity with household income needs, and treat any possible later 721 contribution as a separate decision.
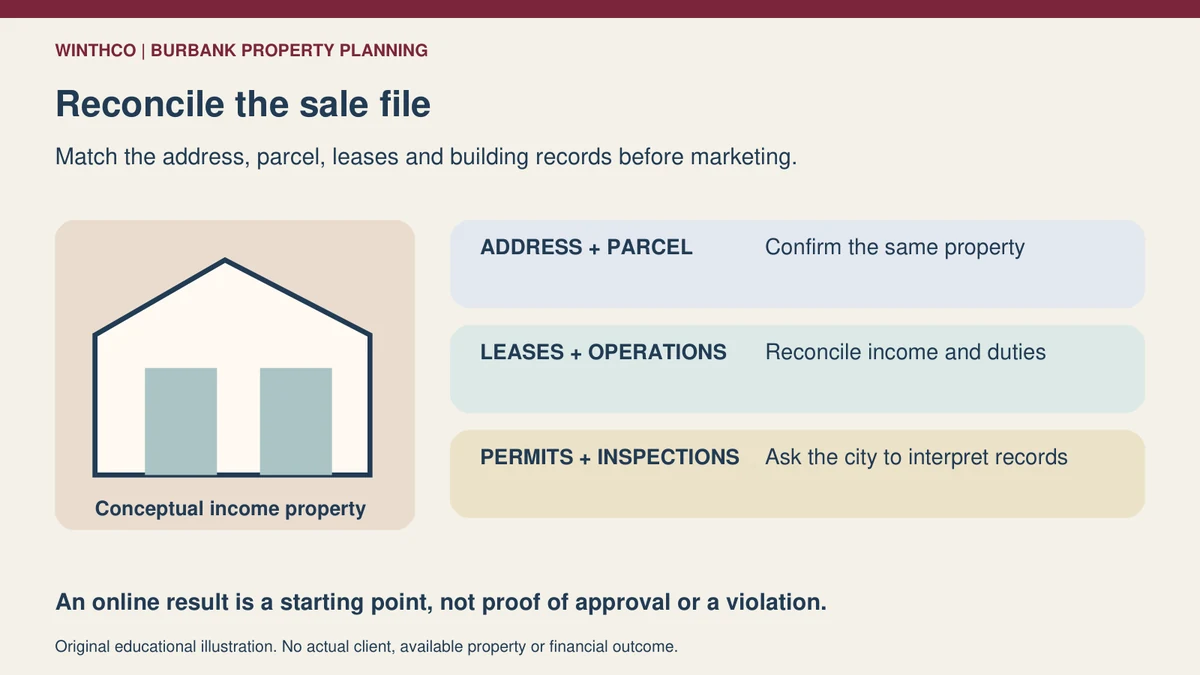
Begin with the reason for selling and the evidence a buyer will need. Interview appropriately licensed residential or commercial real estate professionals who know the property type, whether it is a small rental, mixed-use building or another investment property. Ask how they support the recommended value, market an occupied property, screen buyers, coordinate inspections and explain compensation. Verify the California license rather than relying on a business card or referral alone.
Build a sale file before marketing: current leases, deposit records, operating statements, debt terms, insurance, repair history, permits and documentation for alterations or changes in use. Ask which gaps could affect buyer diligence, financing or closing. If a deferred exchange is being considered, involve the CPA, attorney and qualified intermediary before closing or receipt of sale proceeds. The listing professional handles the sale process; those tax and legal roles are separate.
Share your timeline and investment range. A Winthco team member will follow up with you.
The Census Bureau identifies Burbank as an incorporated California city. Burbank's Public Records Portal says it provides building documents including permits, inspection records and certificates of occupancy. The city's planning and zoning page separately links an interactive citywide mapping tool for parcel-based data. These tools can help organize questions, but an online result does not by itself establish that work was approved, unpermitted or complete.
Confirm the property's jurisdiction, address and parcel before relying on a record. Ask the relevant Burbank department how to obtain and interpret the file, and ask the sale professional which issues require follow-up before marketing. For an occupied property, have counsel review leases, notices and applicable tenant rules. This article does not decide whether a particular permit, zoning classification or tenant rule applies. The map shows Burbank for geographic context, not a Winthco office or parcel boundary.
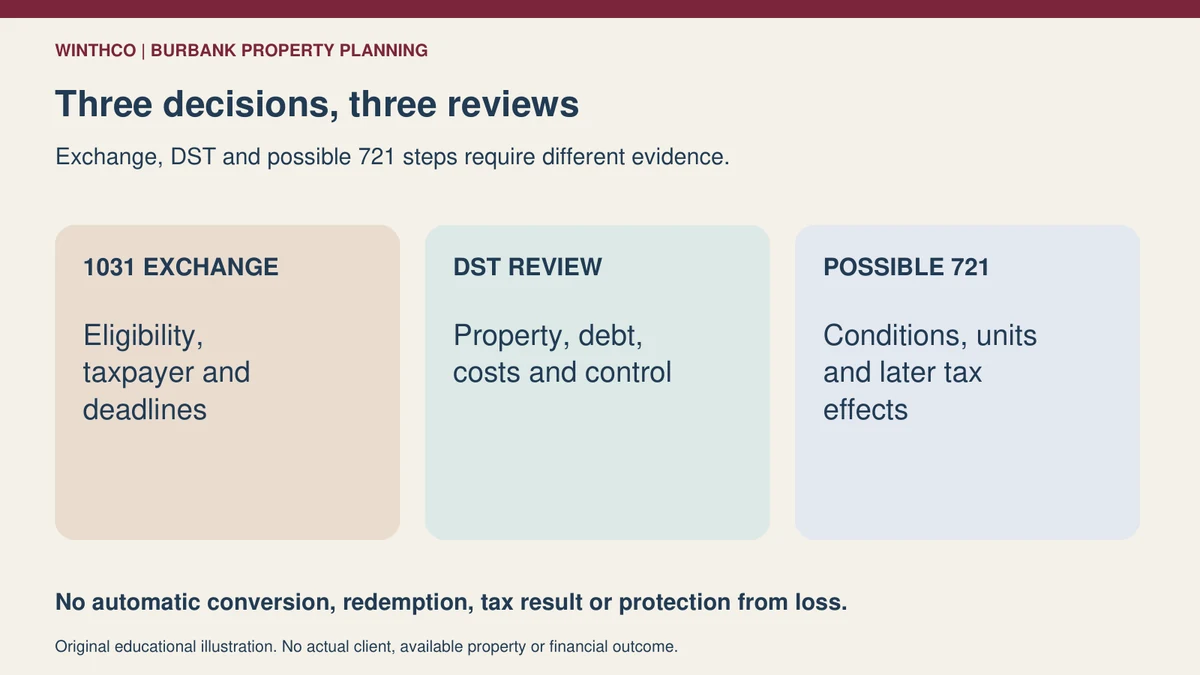
Section 1031 can defer eligible gain when qualifying business or investment real property is exchanged under the applicable rules. Deferral is not elimination of tax. The CPA should examine the taxpayer, use history, adjusted basis, liabilities and state reporting. Compare keeping the property, a taxable sale, a partial exchange and a full exchange. A seller who needs cash soon may reach a different conclusion from an owner focused on continued real-estate exposure.
For an ordinary deferred exchange, replacement property generally must be identified within 45 days after the transfer of the relinquished property. Completion is due by the earlier of 180 days or the applicable return due date, including extensions. Cash retained, nonqualifying property or changes in debt can produce taxable boot. Put the actual dates and responsibilities in writing with the QI and tax preparer. Do not let a deadline turn an incomplete investment review into a rushed subscription.
Discuss your DST questions with Winthco →
A Delaware statutory trust may hold identified real property while investors own beneficial interests. Under the specific facts of IRS Revenue Ruling 2004-86, the beneficial interests were treated as direct interests in real property for federal tax purposes. The ruling does not approve every trust labeled a DST. The taxpayer, exchange and offered interest must satisfy the applicable requirements. The California DST planning overview is background, not a property-specific eligibility opinion.
A DST can shift tenant calls, repair coordination and leasing administration away from an individual owner, but that convenience comes with limited control. Ask who sets rents, uses reserves, handles debt, approves leases and decides when to sell. An expected holding period is not a personal withdrawal right. If the household may need capital for retirement spending, health costs or another purchase, compare that schedule with the investment's actual transfer restrictions and uncertain exit.
DST interests are generally private-placement securities offered to accredited investors. Accreditation does not prove suitability or reduce property risk. Read the private placement memorandum, trust agreement and subscription documents. Confirm the legal entity, property, sponsor, debt and restrictions rather than assuming that every DST follows the same economics or can be sold on demand.
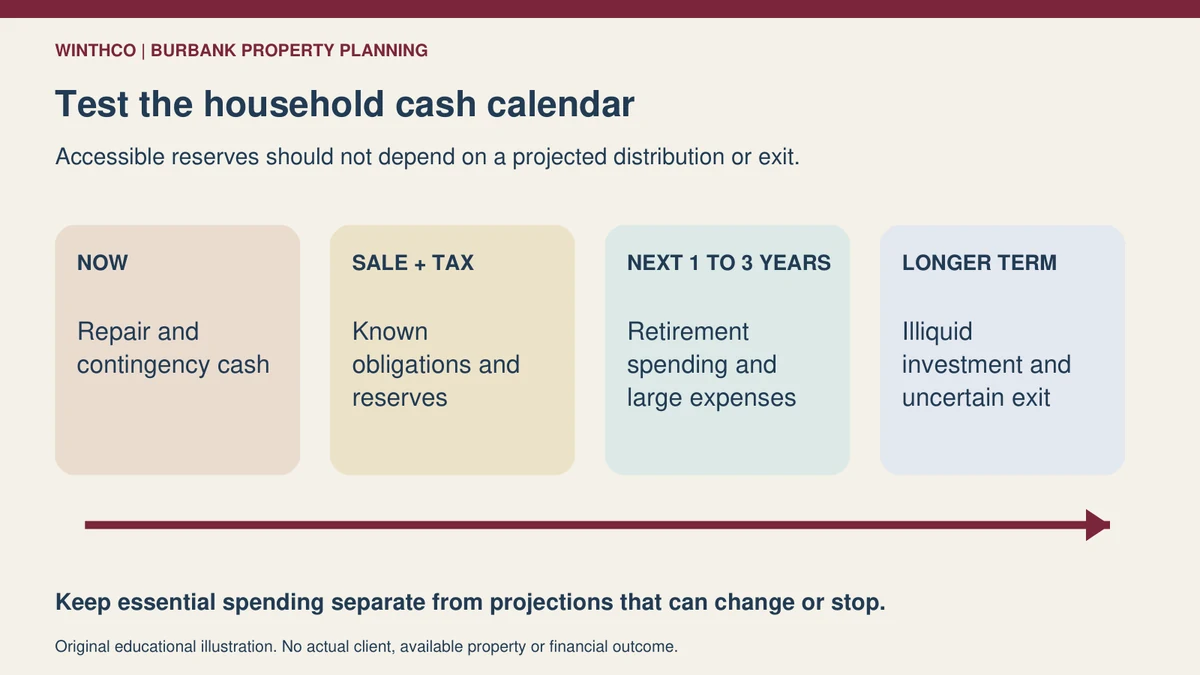
Compare the current property's net cash flow with the proposed DST using consistent definitions. Gross rent is not spendable income after vacancies, repairs, management, insurance, taxes and debt service. A DST distribution may also include assumptions that change. Ask where cash distributions are expected to come from, what expenses are excluded, whether reserves are being funded and how tenant weakness or capital work could reduce payments.
Review acquisition, financing, organization, asset-management, property-management, servicing and disposition costs, including compensation paid to affiliates. The DST risk review explains why fees, leverage, limited control and illiquidity must be considered together. A disclosed fee is still an economic cost, and a projected distribution is not a promise of total return, appreciation or principal protection.
Stress-test the property and the household. What happens if a major tenant leaves, insurance costs rise, financing matures, distributions stop or the property sells later than expected? Several DSTs may still share the same sponsor, lender, property type or economic driver. FINRA's concentration guidance supports evaluating the entire portfolio, including financial assets and hard-to-sell real estate interests.
WATCH & LEARN
Winthco Wealth Management introduces general DST and property-sale planning. This video is not Burbank permitting guidance, a current offering recommendation or a promise of income, liquidity or tax treatment. Review the actual property and offering documents with qualified professionals. Original resource · Watch on YouTube ↗
Educational context only. The discussion does not establish the suitability, returns or tax treatment of an investment.
Section 721 generally addresses contributions of property to a partnership for partnership interests, subject to exceptions and transaction-specific facts. An UPREIT commonly holds real estate through an operating partnership associated with a REIT. That is a different framework from a Section 1031 exchange. Ordinary REIT shares and operating-partnership units generally are not direct 1031 replacement real property. The CPA and attorney should review the proposed steps rather than treating the labels as interchangeable.
Some DST materials describe a possible later contribution to an operating partnership. Ask whether the event is optional, who controls timing, how the property and units would be valued, which conditions remain, and what happens if it never occurs. The initial DST should fit without depending on that future event. Use the DST evaluation questions to organize the offering review, then examine the separate 721 documents if and when a real proposal exists.
Operating-partnership units can have transfer limits, redemption procedures and tax consequences. A minimum holding period does not guarantee conversion, cash or liquidity at its end. FIFO selection does not by itself create tax-free basis withdrawals. Debt allocations, distributions and later redemptions may matter. Compare enforceable rights in the actual documents with household needs rather than relying on an illustration of a possible sequence.
Consider a hypothetical owner preparing to sell a Burbank duplex with an older improvement and two active leases. The owner wants fewer maintenance demands but also expects to supplement retirement spending within several years. No actual client, property or result is represented. The broker and city-record process clarifies the sale file, while counsel reviews the leases and the CPA and QI analyze alternatives before closing.
The owner compares a taxable sale, a partial exchange and DST replacements. The analysis does not assume a distribution amount or a later 721 transaction. Instead, the financial plan identifies accessible reserves for taxes, repairs and spending if a distribution declines or a sale is delayed. That separates the household's cash calendar from the investment's uncertain calendar and makes the trade-off visible before a commitment.
The SEC warns that private placements can provide limited information, be highly illiquid and result in total loss. DST investors also face sponsor, tenant, property, debt, valuation, conflict, fee and tax-law risks. Distributions can change or stop, and principal can be lost. A qualifying exchange does not make the investment suitable or remove these risks.
California follow-up also deserves an owner. The Franchise Tax Board describes Form 3840 reporting when California property is exchanged for out-of-state property and California-source gain or loss remains deferred. Reporting may continue in later years. Keep federal and state records with the transaction file and confirm the actual filing responsibilities with the CPA.
Winthco's wealth-management services can connect the property decision with retirement-income needs, financial assets, 401(k)s, IRAs, asset allocation, liquidity and beneficiary or estate coordination. A property sale does not automatically make a rollover, transfer or advisory relationship appropriate. Compare choices, costs and services separately. Qualified retirement accounts are not themselves 1031 proceeds. Use a prospect form to share the sale stage and planning question, then request a secure channel before sending confidential records.
Burbank, California, for geographic context. This is not a Winthco office or a parcel-boundary determination.
| Decision | Evidence to request | What to avoid assuming |
|---|---|---|
| Keep and hire management | Net cash flow, retained control and workload | Delegating work eliminates property risk |
| Taxable or partial sale | Taxes, flexibility and near-term spending | Every dollar must enter an exchange |
| Qualifying DST exchange | Documents, costs, property, debt and liquidity | Tax eligibility establishes suitability |
| Possible later 721 | Conditions, valuation, unit rights and tax effects | A target date guarantees conversion or cash |
This guide does not claim one. The verified Winthco contact page lists Simi Valley. The Burbank map is geographic context only.
Not by itself. Use the portal to organize questions, then confirm the address, parcel, documents and interpretation with the relevant city staff and professionals.
No. Section 1031 concerns qualifying business or investment real property. Ask the CPA to assess mixed use or a change in use.
No. Confirm each professional's credentials, engagement and responsibilities. Tax analysis, investment advice, legal advice and exchange administration are separate roles.
No. A projection can change or stop and does not promise total return or principal protection. Compare accessible resources and downside cases.
Not necessarily. It may not occur, and any unit transfer or redemption can have restrictions and tax consequences. Review the actual proposal separately.
Sources checked October 22, 2026. This article explains general concepts; your facts and the applicable documents control.
Winthco DST services · Winthco evaluation overview · Editorial standards
1031 replacement property
Compare DST and 721 UPREIT paths, tax rules, ownership, liquidity, control and risks before a property sale or exchange.
Read guide →Alternatives and comparisons
Compare DST distributions with rental cash flow, fees, tax reporting and retirement spending before selling an investment property.
Read guide →DST investment due diligence
Selling a rental property? Learn how to review a DST private placement memorandum, compare fees and risks, and assess separate 721 UPREIT terms.
Read guide →Explore Winthco’s main DST article collection
Share your timeline and investment range. A Winthco team member will follow up with you.