Property sale planning
Before Listing a Rental: DST and 1031 Planning
Prepare a rental sale with broker questions, 1031 timing, DST and separate 721 review, and retirement planning before committing proceeds.
Read guide →
Home / Learning center / Local DST guides
Local DST guides
Winthco Wealth Management · Updated November 11, 2026
Before selling a Hermosa Beach investment rental, ask your broker to value the property as it is and separate any premium based on future redevelopment. Confirm coastal and other approvals with the appropriate agencies, arrange any deferred 1031 exchange before closing, and judge a replacement DST on documented cash flow and risks rather than upside assumptions.
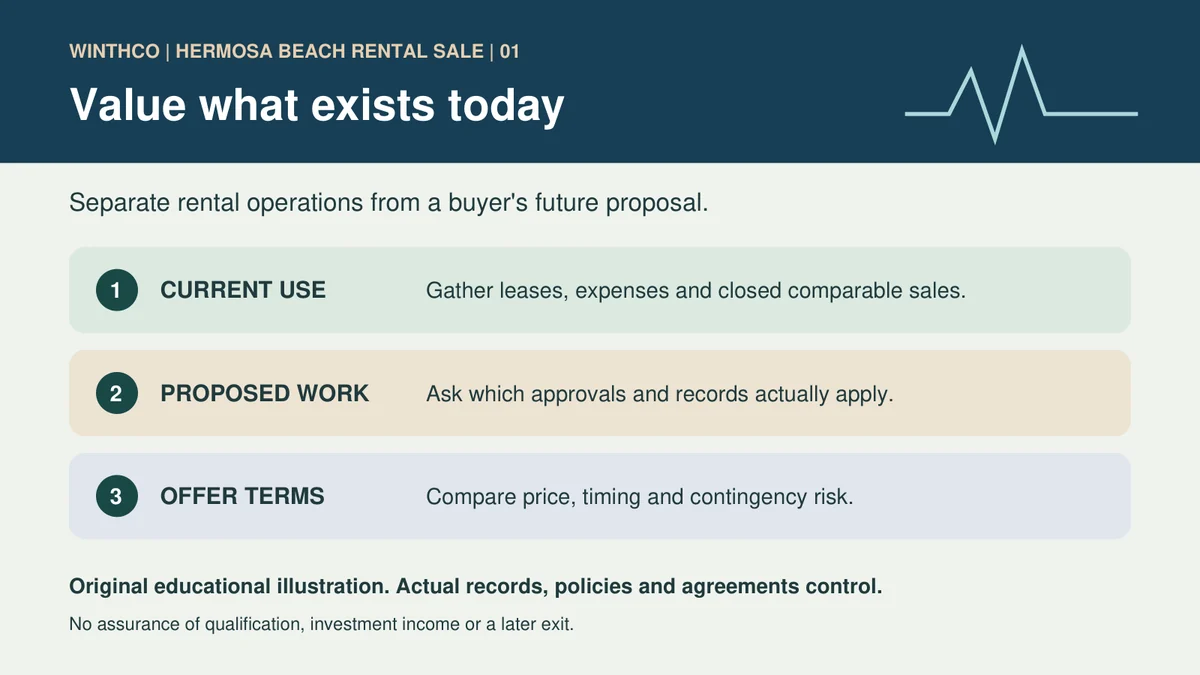
Look for a licensed broker who has closed sales of occupied investment properties with similar leases, condition and financing constraints. Ask for closed comparable sales, not just asking prices. Have each broker explain how they adjusted for occupied units, lease terms, operating expenses and any redevelopment assumptions. Compare their fee and marketing plan, how they would describe a possible future use without overstating it, and who will coordinate tenant notices, due diligence and escrow. Bring the leases, rent roll, utility bills and recent capital invoices. A useful valuation separates income a buyer can underwrite now from improvements a buyer might someday pursue.
A California Coastal Commission staff report on a Hermosa Beach project distinguishes the city's certified land use plan from a certified local coastal program. That report concerns a particular application, not a finding about your parcel. Give the city planning staff and, as appropriate, Coastal Commission staff the address, existing use and specific work a buyer is contemplating. Ask which documents and approvals apply and whether old conditions still matter. Request written records rather than relying on a broker's description of what could be built. If the buyer's price depends on a future approval, have counsel review the contingency, the party who bears the cost and the date the buyer can walk away.
Share your timeline and investment range. A Winthco team member will follow up with you.
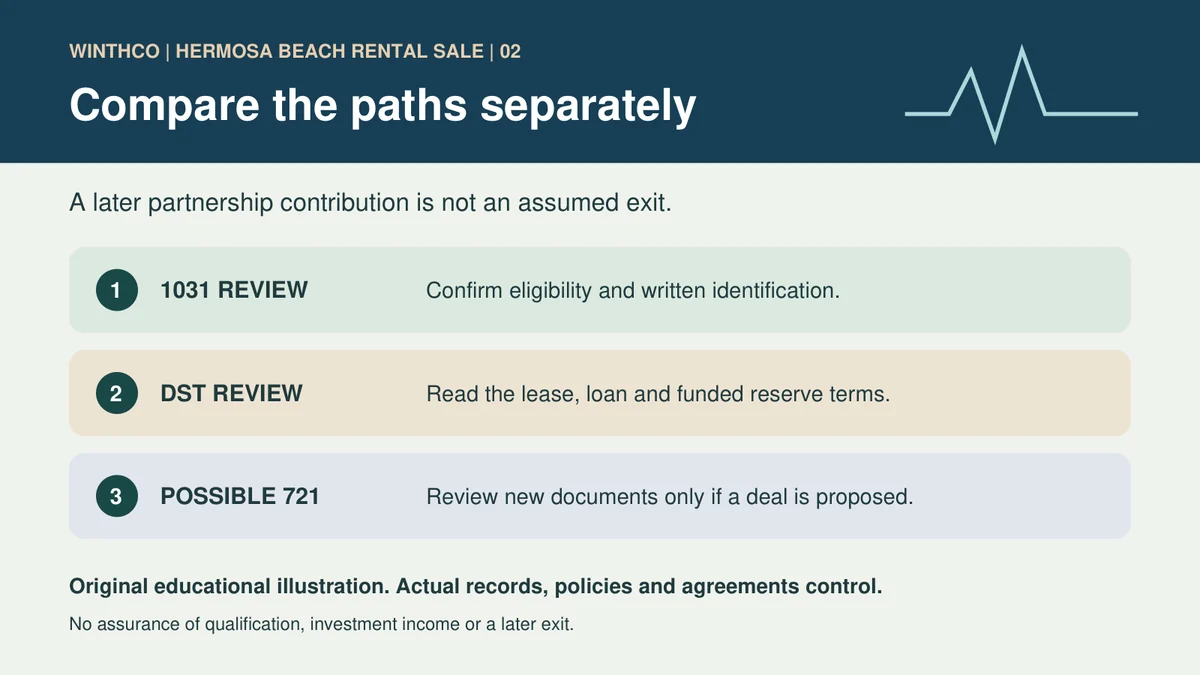
Suppose a buyer values a Hermosa Beach duplex as a rental but offers more if an addition proves feasible. Ask the broker to compare a simpler offer with a longer contingent one on proceeds, closing certainty and the owner's carrying costs. Bring a CPA, attorney and qualified intermediary into the process before closing or receiving proceeds. Under the deferred exchange rules, identify replacement real property in writing within 45 days after transfer and receive it by the earlier of 180 days after transfer or the federal return due date, including extensions. A delayed sale may shift the start date, but a delay acquiring the replacement does not restart the clock. Winthco's overview of DST replacement property explains one possible route.
Discuss your DST questions with Winthco →
Ask the CPA to compare a taxable sale, a qualifying exchange and a scenario where part of the gain is recognized. Provide your adjusted basis records, depreciation, proposed credits, mortgage payoff and draft settlement figures. Cash or other non-like-kind property received, and the treatment of liabilities, can affect recognized gain. A smaller wire after paying off a loan does not by itself establish the amount of gain. Section 1031 can defer eligible gain when the requirements are met; it does not eliminate the tax. If California real property is exchanged for out-of-state real property, ask about initial and continuing Form FTB 3840 reporting. Do not assume buying outside California erases California-source deferred gain.
Direct ownership can let you decide how to lease, maintain or improve the replacement, subject to law, financing and contracts. A DST can reduce those day-to-day duties, but you generally give up control over major decisions. IRS Revenue Ruling 2004-86 addresses the particular trust and interests described in it, not every trust with a Delaware label. Have your tax and legal advisers review the actual structure and your exchange facts. For investment review, use Winthco's guide to evaluating a DST offering alongside the private placement memorandum, trust agreement, lease materials and debt summary. Write down which decisions are yours, which belong to the trustee or manager, and what each party may do when results differ from the offering assumptions.
WATCH & LEARN
Accruit introduces DST interests as possible 1031 replacement property. This third-party video is general education, not a review of a Hermosa Beach property or a recommendation of any investment. Original resource · Watch on YouTube ↗
Educational context only. The discussion does not establish the suitability, returns or tax treatment of an investment.
Start with leases in force, rather than projected renewals. Identify who pays property taxes, insurance, recurring repairs and major replacements. If there is a master lease, distinguish the rent the trust is owed from the income the underlying property generates, and ask how the master tenant would cover a shortfall. Look for concentration by tenant, lease rollover date and market. Then compare contract rent and property expenses with the cash available after debt service and reserve funding. A well-presented forecast is not a contract. The DST reserve and capital repair guide helps identify costs that can fall outside the day-to-day operating budget.
Use a simple downside case: a major tenant leaves, improvements are required to attract a new tenant, and the loan matures before leasing stabilizes. Ask which costs funded reserves could cover, who controls those reserves and what happens if they fall short. Review rate terms, maturity and any extension conditions in the loan documents. Distinguish the actual loan provisions from an assumption that refinancing will be available. Compare fees paid up front, through operations and at sale, including compensation paid to affiliated parties. Two offerings with similar initial distributions can differ substantially in debt exposure, conflicts and cash available for reinvestment.
Private DST offerings are generally directed to accredited investors and disclosed in offering documents. An interest may be hard to value or sell, and there may be no practical exit when you need cash. Sponsor decisions, property and tenant performance, leverage, refinancing and concentration can all affect results. Distributions can decline or stop, holding periods may exceed expectations, and investors can lose principal. Owning several DST interests does not remove shared exposure to the same sponsor, tenants or financing conditions. Compare those risks with a directly owned replacement, a taxable sale and keeping enough accessible assets outside the property decision. A deadline is not a reason to buy an investment you otherwise would decline.
No. A possible Section 721 contribution to an operating partnership is a separate transaction and may never be offered or completed. Ordinary REIT shares and operating partnership units are not direct Section 1031 replacement real property. Evaluate a DST on its own terms first. If a later contribution is proposed, have counsel and your CPA review the agreement, valuation, liabilities, possible tax consequences and any election or transfer restrictions. Compare operating partnership units with REIT shares instead of assuming the two can always be exchanged on demand. Ask what happens if the expected conversion or redemption is unavailable when you need it.
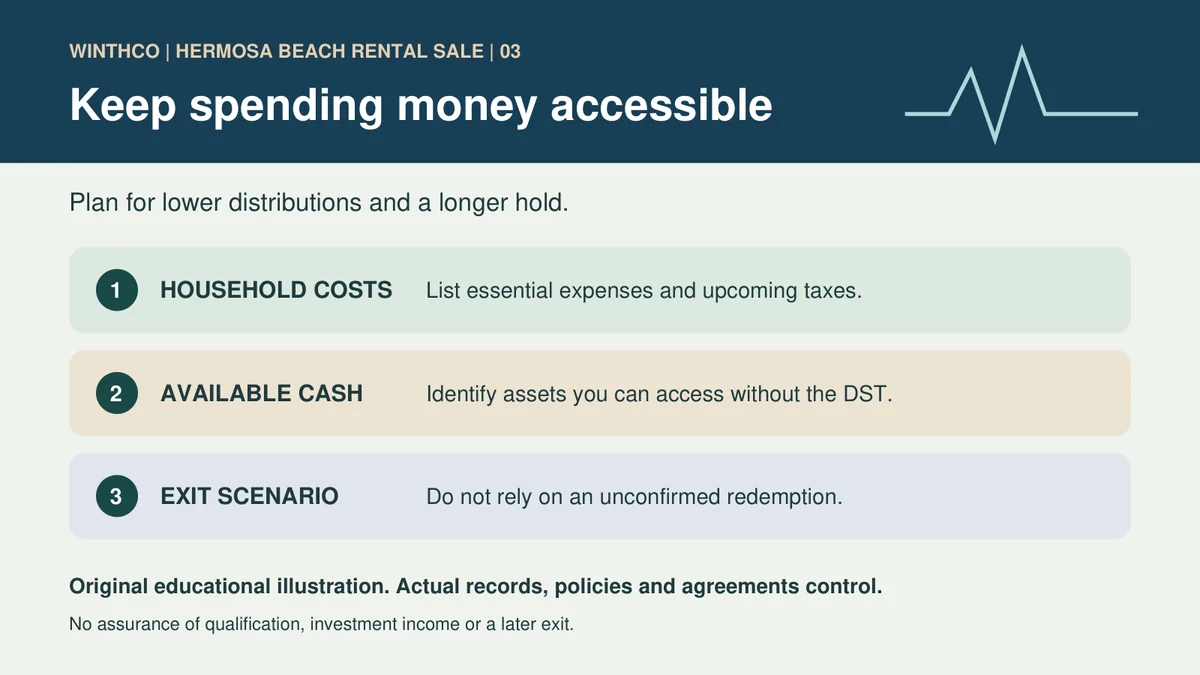
Make a list of upcoming tax payments, essential spending and cash reserves outside the exchange. Check whether those expenses remain covered if a distribution stops or the property is held longer than expected. Review your taxable assets, existing 401(k)s and IRAs, investment expenses, account services and beneficiary instructions. Retirement account assets are not exchange proceeds, and a property sale does not make a rollover necessary. Winthco Wealth Management can help assess household income, allocation and concentration alongside your tax and legal advisers. Ask each professional to identify decisions that must be made before closing and decisions that can wait until you have more information.
Ask the broker for a written comparison of the offers and the assumptions behind each price. Have counsel identify unresolved approvals, title restrictions and contractual deadlines. Request a CPA estimate under more than one sale and replacement scenario. Ask the intermediary for a dated identification and funds-handling checklist. A financial advisor can help compare the proposed investment's cost, concentration and cash needs with the rest of your portfolio. Put the findings on one sheet with a decision date and a person responsible for every open item. If a critical assumption cannot be verified before the deadline, compare walking away with proceeding on incomplete information.
City-area context only. Not a coastal-zone boundary, parcel map or Winthco office.
| Decision | Evidence to request | What to avoid assuming |
|---|---|---|
| Sale underwriting | Current leases, actual expenses and contingent redevelopment value | An asking price proves redevelopment is permitted |
| Deferred exchange | Written identification, earlier closing deadline and CPA tax scenarios | Closing extensions reset the clock |
| DST review | Lease economics, funded reserves, debt and conflicts | An illustrated distribution is a commitment |
| Household liquidity | Assets available independently of the DST | A later 721 transaction or redemption is certain |
Do not assume a sale alone triggers a particular development approval. Check the parcel, existing permits and proposed work or use with the appropriate planning and coastal staff.
It can be considered if the interest and transaction meet the applicable requirements. Have your CPA and attorney review the trust documents and exchange facts before committing.
No. The deferred exchange clock generally starts when you transfer the relinquished property. Have your qualified intermediary confirm the dates from your actual closing.
Do not assume so. Verify the credentials and scope of each professional and engage qualified tax and exchange specialists separately.
No. Judge the DST without an assumed conversion or redemption. Any later contribution has separate documents, risks and tax questions.
Sources checked November 11, 2026. This article explains general concepts; your facts and the applicable documents control.
Winthco DST services · Winthco evaluation overview · Editorial standards
Property sale planning
Prepare a rental sale with broker questions, 1031 timing, DST and separate 721 review, and retirement planning before committing proceeds.
Read guide →DST due diligence
Before exchanging a rental into a DST, review repair budgets, restricted reserves and funding limits. Know which questions to ask before committing.
Read guide →Local DST guides
Selling an occupied Glendale rental? Verify tenant obligations before setting a closing date and comparing a 1031 exchange, DST and retirement cash needs.
Read guide →Explore Winthco’s main DST article collection
Share your timeline and investment range. A Winthco team member will follow up with you.